Payroll Approval Process: How to Review Payroll Before You Hit Send

Key Takeaways
- A payroll approval process sits between calculation and funding. It should test the items that usually break.
- Before anyone signs off, reconcile approved timekeeping hours to payroll hours, and this register to the last one.
- Regular-rate overtime, multi-site hours, rate changes, and direct deposit changes deserve a line-by-line look every cycle.
- Exception reports with tuned thresholds shrink the review to the lines that actually moved.
Once the bank file goes out, every mistake in it becomes a recovery project. An overpayment means asking an employee to hand money back. An underpayment means an off-cycle check and a worker who now reads every stub line by line. The payroll approval process is the window between "payroll is calculated" and "payroll is paid," where someone with context looks at the numbers and agrees they make sense.
Most teams already have a version of it. Usually one person compares the register total to last period and clicks submit if it looks close. That catches a missing location. It won't catch an employee paid for 112 hours. It won't catch overtime calculated on base pay when a shift differential should have been in the rate.
Why Payroll Needs a Formal Approval Step
Payroll is the largest payment most companies send without matching it to anything. Accounts payable has purchase orders and receipts. Payroll has a calculation engine and whoever happens to run it that week.
Garbage in, garbage out applies here like anywhere. Hours arrive from a wall clock or a phone app, or, on a bad week, from a supervisor retyping a crumpled paper sheet on Monday morning.
Rate changes come from HR, deductions from benefits. Each handoff is a place for a number to change shape, and the person pressing submit didn't touch most of them.
Wage errors get expensive when someone else finds them first. The US Department of Labor's Wage and Hour Division recovered $149.9 million in back wages under the Fair Labor Standards Act in fiscal 2024, and about 85 percent of it was unpaid overtime. Most payroll errors never reach an investigator. They sit in the data as small overpayments and underpayments that repeat every cycle, which is how the real cost of payroll errors ends up far larger than any single mistake.
Fraud is the other reason. PayrollOrg's summary of the ACFE's 2026 Report to the Nations puts the median payroll fraud scheme at 13 months before anyone catches it, at roughly $4,800 lost per month. Thirteen months on a biweekly schedule is 28 pay runs. Twenty-eight approvals where nobody looked at the right line.
A formal step changes the question from "does the total look right?" to "did someone check the things that usually go wrong?" It also leaves a record. When a payroll audit or a wage claim asks who approved a pay run, "we always eyeball it" is a hard answer to defend.
Who Should Be Involved in the Payroll Approval Process
The best practice here is segregation of duties. Whoever edits payroll data doesn't approve it. Whoever approves it can't be the only one able to move the money. A three-person finance team will bend this a little, and that's fine, as long as you know where you bent it.
Time gets approved by whoever is closest to the work, usually a supervisor or site manager. They know whether someone actually worked Saturday, or whether a missed punch got filled in with a guess. For hourly and deskless staff, this is the only point in the chain where the approver has seen the work happen. No supervisor should approve their own timecard. That sounds obvious until you find the shift lead who is hourly, runs a site alone on weekends, and is the only approver configured for it.
The preparer runs the cycle. Give that same person the keys to add employees and edit bank details, and you've set up a ghost-employee scheme that only needs the wrong hire. Route those two changes past somebody else.
Then there's the reviewer. Often that's the controller, sometimes an HR lead who knows payroll better than anyone admits. They work the checklist below, ask annoying questions, and sign. They don't re-key anything.
The releaser authorizes funding, either by transmitting the bank file or approving the provider's ACH debit. One person can review and release, as long as they didn't also prepare the run.
Got a team of two? That's still enough. One person preps, the other approves and pushes the money. Keep a running log of new hires, rate changes, and direct deposit edits, and have the approver actually read it every cycle, because that log is where a ghost employee or a rerouted paycheck shows up first.
{{celery}}
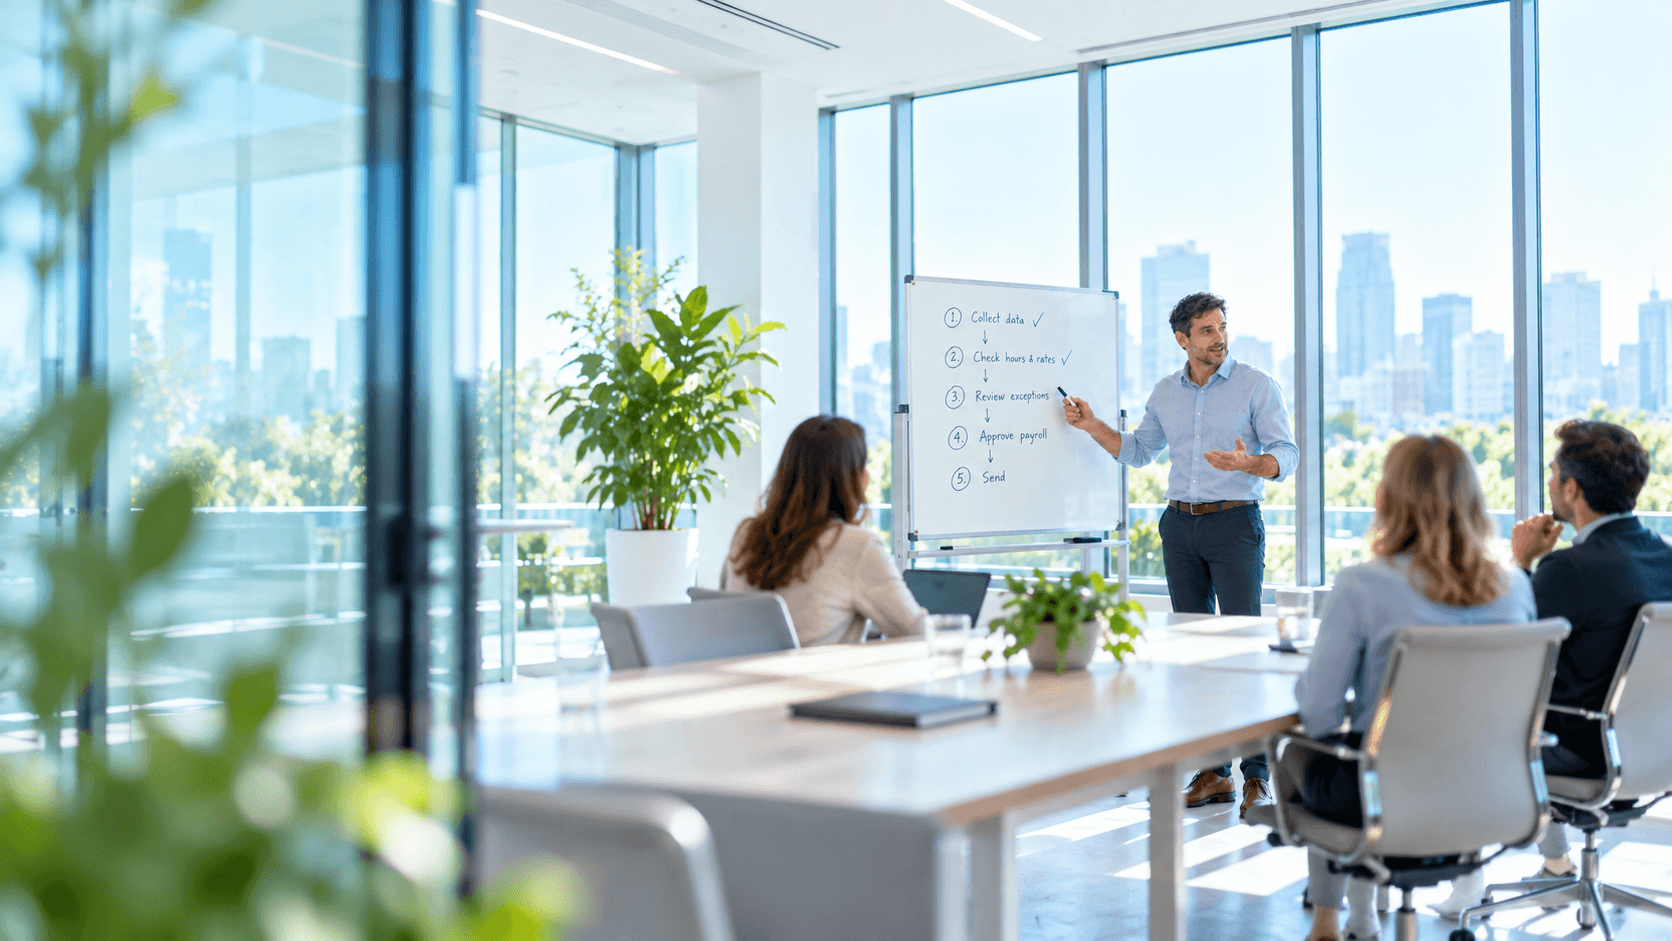
Mapping the Payroll Approval Workflow From Timesheets to Release
Timecard close and supervisor approval
The period ends, and supervisors get a fixed window, often until noon the next business day, to clear missing punches and unapproved overtime. Require a reason code and the editor's name on any change to an employee's own punch. When an 11:52 pm clock-out quietly turns into 10:00 pm, you want to know who did it and why, ideally before the employee asks.
Import and headcount check
Once approved hours land in payroll, hold off on calculating. Do a headcount first. Three lists: active employees with hours, active employees without hours, and anyone with hours who isn't active. An employee terminated on the 3rd with hours on the 9th is either a data error or something worse.
Change entry
Master-file changes and one-time payments go in. Each should trace back to a document, like a signed status change or a benefits election. No document, no change this cycle.
Preliminary register and payroll reconciliation
Now run the numbers, but don't commit them. Payroll reconciliation lives here. Put this register next to last cycle's and go employee by employee, then by site and earnings code, writing a one-line reason for every gap that matters. Total hours in payroll should equal total approved hours in timekeeping. Off by even six hours? Stop and find them.
Review and sign-off
Questions go back to the preparer, answers come back, and only then does the reviewer sign. In the system, with a timestamp.
Release
Before funding, the releaser checks one thing: does the final total match what was approved? Anything changed after sign-off goes back through review. A "quick fix" after approval is how an approved $412,000 payroll turns into a $438,000 one that nobody approved.Line Item
Line Item Reviewers Should Verify Before Signing Off
A payroll checklist that just says "check overtime" won't get anyone to check overtime. Here's what to look at each cycle when a lot of your people are hourly and spread across sites.
Hours that don't match reality
Pull two lists: anyone over 60 hours for the week, and anyone who hit their scheduled hours exactly, to the minute, every day. Sixty-plus is usually a double import or somebody who never clocked out on Thursday. Perfect-to-the-minute usually means a supervisor approved the schedule, not the punches. Then check people who worked at two sites in the same week. Their hours have to be combined for overtime, and when two managers approve them separately, they often aren't.
Overtime on the regular rate
This one trips up good payroll teams. The FLSA says overtime is owed on the regular rate, and the regular rate folds in shift differentials and most non-discretionary bonuses. Say someone earns $20 an hour, works 45 hours, and 20 of those were nights paying $2 extra. Straight time comes to $940: $900 in base, $40 in differential. Spread over 45 hours, the regular rate is $20.89. Half of that on five OT hours is $52.22 in premium. A system set up the lazy way pays $50, time and a half on the $20 base. The gap is $2.22 for one person in one week. Multiply by 300 night-shift employees and 26 pay periods and it's over $17,000 a year. That's exactly the math a wage-and-hour investigator runs. In states with daily overtime rules, check daily totals too.
Rate changes and retro pay
Every rate change should match an approved change on file with the right effective date. A raise that lands mid-period needs the hours split at that date. Confirm any retro pay owed from last period is in this run.
New hires and terminations
New hires need a start date inside the period and tax setup for the state where they actually work. Remote and traveling employees are the usual suspects for wrong state withholding. Terminations are messier. Some states want the final check on the last day worked, so a termination keyed in late can already be a violation by payday. Terminated employees should have no future hours or active recurring payments.
Bank and deduction changes
Any direct deposit change from the past 30 days deserves a second look, especially one requested by email or one of several changes in the same week. Garnishments should be at the right amount and priority. Benefit deductions should start when coverage did. And no deduction should push someone's pay below minimum wage.
Off-cycle and one-time payments
Bonuses, manual checks, a reimbursement someone slipped into payroll: each needs a sign-off from outside payroll, and supplemental-wage tax treatment where it applies.
Using Exception Reports to Speed Up Payroll Review
The truth is nobody reads all 2,000 lines of a register every other Tuesday. An exception report hands the reviewer the 40 that moved.
It compares each person's pay to what's normal for them (usually their own last six cycles, or peers in the same role and site) and flags whatever falls outside a band. Some bands to start with:
- Gross pay up or down more than 20 percent from the employee's trailing average
- Net pay at zero, negative, or above a set ceiling
- More than 12 hours in one shift or 60 in one week
- Overtime above 15 percent of total hours at any single location
- Pay with no hours, or hours with no pay
- The same bank account on two different employees
Your first run will be noisy. If people on variable shifts trip the 20 percent rule every cycle, loosen it for them, or compare to the same pay period last year. Three hundred flags is just a shorter register, and it'll get skimmed the same way.
Write down what each flag turned out to be. Give it three or four cycles and patterns show up: the site where missed punches always get filled in at eight hours, or the team that never shows overtime even though the schedules say it should. That's where your next payroll audit starts.
Spreadsheet rules only catch what someone thought to write a rule for. Celery is an AI-powered payroll protection platform that runs every pay run through more than 100 checks before submission and explains why each exception was flagged. That way, errors get caught before money moves. When one does slip past, the order of the fix matters, and we've laid it out in our guide to correcting payroll errors.

Add an automated protection layer
Use Celery to review every payroll, line by line, before money moves.
FAQs
Work back from your provider's funding cutoff, then add a buffer. Standard direct deposit usually needs submission two to four banking days before payday, depending on the provider. Aim to finish approval a full business day before that cutoff, so a question raised in review doesn't force a choice between paying late and paying wrong. Watch bank holidays, since one inside the window moves the cutoff a banking day earlier.
It depends on whether the money has left. Before the bank file transmits, most providers let you void and re-run. After it goes out, fix underpayments with an off-cycle payment quickly, since many states set deadlines and penalties for unpaid wages. Overpayments are harder: recovery rules differ by state, and many require written employee consent before deducting. Either way, log the error and its root cause.
Yes, and they arguably need it more. Small payrolls often run through one person who enters data, calculates, and releases funds, which is the exact setup that lets mistakes and fraud run for months. A light version works fine: the owner or an outside accountant reviews a variance summary and the change log each cycle, and keeps release authority with the bank.
For each pay run, keep the preliminary and final registers, the exception report with how each item was resolved, the master-file change log, and timestamped sign-offs from the reviewer and releaser. Approvals captured in a system beat email because they can't be edited later. The IRS expects employment tax records kept at least four years. File everything by pay date so an auditor can pull one cycle.
Yes. Most payroll and timekeeping systems support electronic approval with role-based permissions, and mobile approval helps supervisors who spend the day on the floor instead of at a desk. Require multi-factor authentication for anyone who can approve or release funds. Verify any change to bank details or to the approval chain through a second channel, such as a call to a known number, before acting on it.